
Fair Credit Reporting Act Litigation · Nationwide
They got your report wrong. We make them pay for it.
We sue credit bureaus, background check companies, and tenant screeners in federal court when false reports cost you credit, a job, or a home. You pay nothing out of pocket. When we win, the law makes them pay our fees.
Free Case Review
Step 1 of 3 · 60 secondsSubmitting creates only the limited investigation engagement described in the agreement, not full representation.
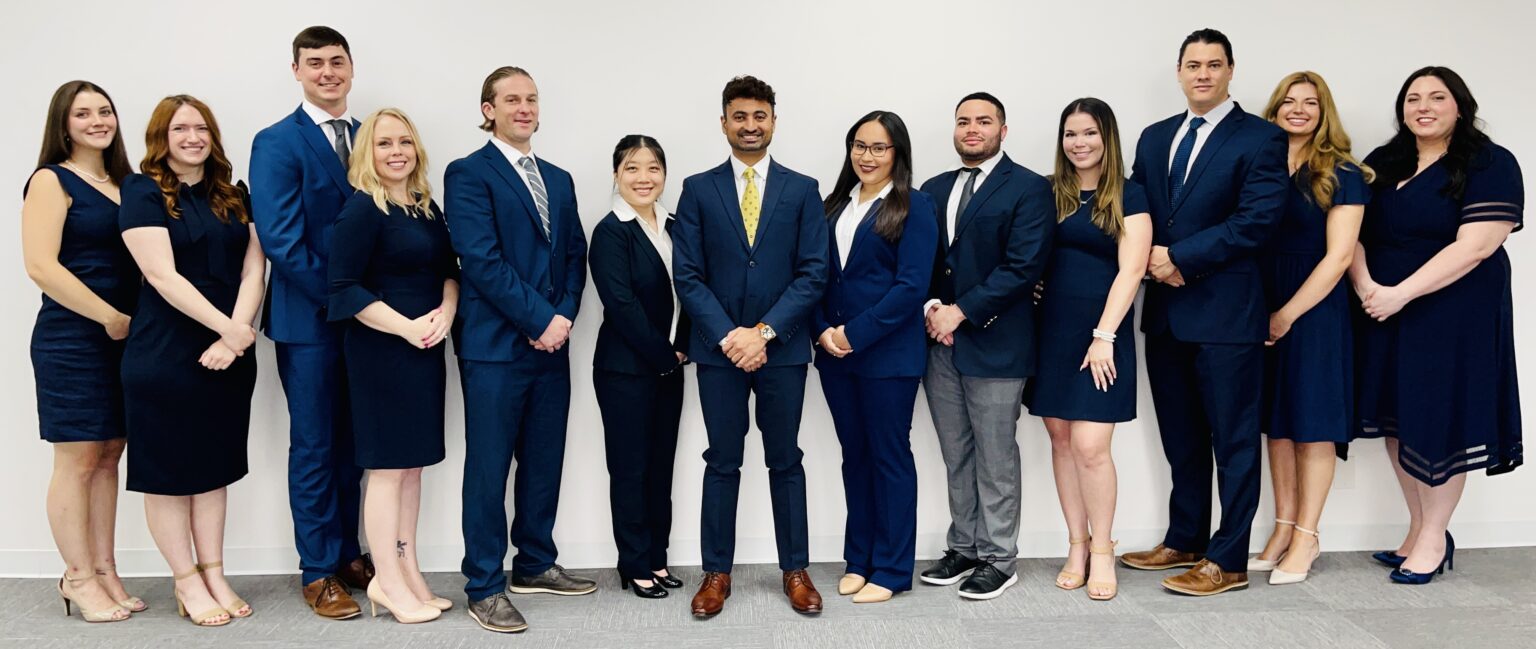
Our team
One law. One focus. A full team behind every case.
Results
Credit bureaus count on you giving up. We don't.
Every number below is money a company paid, or was ordered to pay, because it reported something false and refused to fix it.
Past results do not guarantee a similar outcome. Each case is different and depends on its own facts and law.
Cases we take
What happened to you?
These aren't "mistakes." Under federal law, inaccurate reporting is a violation, and the company that did it can owe you damages.
A bureau won't fix your report
Wrong balances, accounts that aren't yours, paid debts showing as owed, and disputes answered with a form letter.
Credit report lawsuitsMixed filesYour file is mixed with a stranger's
Someone else's debts, addresses, or criminal record on your report, often a relative or someone with a similar name or SSN.
Mixed file casesDeceased indicatorYou've been reported dead
A single false code freezes your credit entirely. These are among the most serious, and most valuable, FCRA cases.
Reported deceasedEmployment screeningA background check cost you the job
Records that aren't yours, dismissed or sealed charges, or old items reported past the legal limit.
Background check lawsuitsTenant screeningA screening report cost you the apartment
False evictions, someone else's criminal history, or debts that were never yours, sold to landlords as fact.
Tenant screening lawsuitsIdentity theftFraud accounts are wrecking your credit
You reported the fraud and blocked it, and the bureaus and creditors kept reporting it anyway.
Identity theft casesHow it works
Three steps. Zero cost to you.
The FCRA was written so that people could afford to fight back. The company that broke the law pays the legal bill.
We review your case
An attorney reviews your report, your denial letters, and what it cost you, and tells you plainly whether you have a claim.
We file in federal court
We sue the bureau, screener, or furnisher in U.S. District Court and handle every filing, deadline, and negotiation.
They pay and fix it
We push for compensation and a corrected file. Our fees are paid by the defendant, not taken from your pocket upfront.
15 U.S.C. §§ 1681n and 1681o. What you can recover depends on the facts of your case.
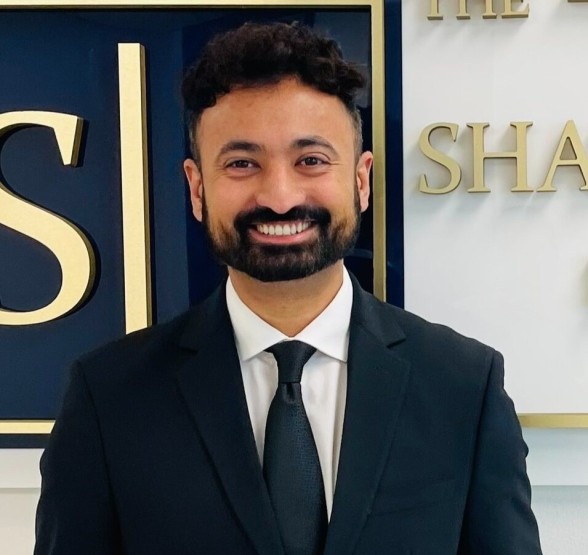
Founding attorney
A finance background, aimed at the companies that profit from your data.
“The bureaus and screeners have built a business on reporting fast and correcting slowly. We make slow expensive.”
Shawn Jaffer founded FCRA Attorneys to take on credit bureaus, background screening companies, and the financial institutions that feed them bad data. Before law school, he built a career in finance, so he reads a tradeline the way the defendants' analysts do.
The firm focuses on one federal law and litigates it nationwide, with offices in Dallas, Houston, Chicago, Los Angeles, and Atlanta.
Know who you're up against
Lawsuit guides by company.
How each bureau and screener handles disputes, the errors they make most, and what a case against them looks like.
Questions
Straight answers.
Still unsure? A free review takes about a minute, and an attorney will tell you where you stand.
What does it cost to hire you?
Nothing out of pocket. We work on contingency, and the FCRA requires a company that violates it to pay your attorney's fees and costs when you win. If we don't win, you owe us no fee.
How much is an FCRA case worth?
It depends on the harm. The FCRA allows actual damages (lost credit, jobs, housing, higher interest, emotional distress), statutory damages of $100 to $1,000 for willful violations, punitive damages, and attorney's fees. Every case is different and past results do not guarantee a similar outcome.
How long do I have to sue?
Generally two years from when you discovered the violation, and no more than five years from when it happened (15 U.S.C. § 1681p). Waiting can cost you your claim.
Do I have to dispute the error first?
A written dispute strengthens most cases and is required for some claims, but not all. Talk to us before you send anything, because how the dispute is written matters.
Will this hurt my credit or my job search?
No. It is illegal for a creditor or employer to retaliate against you for exercising your FCRA rights, and a successful case usually forces the correction of your file.
Do you handle cases in my state?
FCRA claims are federal, and we represent people from every state. We can often file where the company that reported you is based, in a court where our attorneys are admitted (for example Equifax in Atlanta or Experian in Texas and California), or in your local federal court with local or cooperating counsel.
The clock is running
You may have as little as two years to hold them accountable.
Every month a false report stays on your file costs you. Find out in about a minute whether you have a case.